

Since 2005, we’ve helped over 3,600 Australians achieve their financial goals.

Property Investment Strategy Australia
A written plan built before any property is looked at, covering the goal, the borrowing capacity, the criteria and the sequence.
A property investment strategy australia wide should give you clarity before you buy. Reventon helps clients build a written investment property strategy that connects the plan, the finance and the long term outcome before a property is recommended.
Book Your Free Discovery Meeting
Start with clarity. Speak with our team about your property investment goals.
Property investment should be strategic, not emotional
Without a plan, investors often buy what is marketed to them rather than what fits the goal. Reventon builds the strategy first, tests it against borrowing capacity and reviews it as circumstances, lending conditions and tax rules change. The aim is simple. Every property decision should have a reason behind it.
21+
Years in Business
10000+
Clients Helped
3600+
Homes Sold
70+
Industry Awards
700+
5 Star Reviews
170+
Publications

What your strategy covers
A strong property investment strategy firm should help you understand what to buy, why it suits your position and how each decision supports the next step.
Investment strategy
Tailored guidance based on your goals, financial position, timeline and long term objectives.
Established property opportunities
We act on your behalf to identify, assess and secure suitable opportunities that fit the strategy.
New build opportunities
Carefully selected new build opportunities aligned with long term performance. Learn more about new build property investment.
Vendor advocacy
We manage the selling process on your behalf when it is time to exit, consolidate or redeploy capital.
Finance structuring
Lending strategy and finance structure so the plan is built on the right foundation.
Portfolio planning
A long term property portfolio strategy via a secure online portal, with ongoing guidance as the plan develops.
Why it works
Strategy and finance are built together, not separately
A property investment strategist should not build a plan in isolation from finance. Borrowing capacity determines what is possible, while strategy determines what is sensible. Reventon’s in house brokers work alongside the strategy team so the plan is practical from the start.
- Borrowing capacity determines what is possible
- A poorly structured first loan can limit the second purchase
- Our in house brokers work alongside the strategy team
- One plan, one team, one direction
Long term property investment strategy
A long term property investment strategy should be built for more than one interest rate cycle. Property is usually held over many years, so the plan needs to account for cash flow, loan structure, equity growth, rental position and future borrowing capacity.
The right strategy may consider:
- How long each property may be held
- When equity may be reviewed
- Whether a new build or established property suits the plan
- How the property will be managed
- Whether the next purchase should be in the same state or another market
- When to refinance, pause, hold or sell
A strategy should not be rebuilt every time conditions change. It should be strong enough to guide decisions while flexible enough to be reviewed when life, lending or legislation shifts.
Property portfolio strategy
A property portfolio strategy focuses on how multiple properties work together over time.
The first purchase affects the second. The second affects the third. That is why sequencing matters.
A portfolio strategy may cover:
- Purchase order
- State by state exposure
- Property type mix
- Cash flow across multiple loans
- Serviceability after each purchase
- Land tax considerations
- Ownership structure
- Rental property investment strategy
- Refinancing points
- When to consolidate or sell
Reventon helps clients think beyond a single property. The goal is to understand how each decision supports the broader plan, not simply to keep buying without structure.
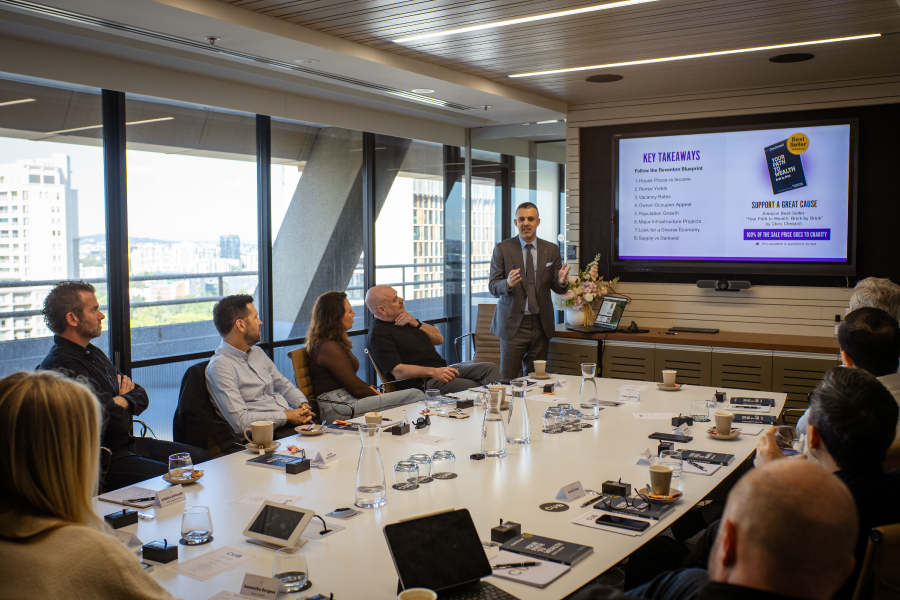
Strategy in a changing tax environment
Property investment strategy now needs to account for a changing tax environment. Recent changes and proposed reforms may affect how investors think about established property, new builds, SMSF structures, deductions and long term holding plans.
Reventon reviews strategies as conditions change, but tax advice should always be confirmed with a qualified adviser.
You can explore Reventon’s negative gearing calculator, learn more about tax minimisation or read the guide to buying property through an SMSF.
A long term wealth partnership
Reventon provides an end to end solution in house, including finance, strategy, acquisition, property management and portfolio growth. That means the same team can support the client before the purchase, during ownership and as the portfolio develops.
Traditional property groups often hand clients off at settlement. Reventon stays connected to the bigger picture, so the strategy can be reviewed against finance, property performance, management outcomes and future goals.
For the broader process, visit our property investment consultant page.
Australia wide investment opportunities
Reventon helps clients assess property opportunities across Australia. The strategy may point to one market or several, depending on borrowing capacity, cash flow, risk profile and long term portfolio direction.
Tailored investment strategies
Every strategy is built around the client’s goals, financial position, timeline and risk tolerance. The right plan should explain why a property type, location and purchase order have been recommended.
Lifetime partnership
The relationship does not end once a property is purchased. Reventon continues supporting clients through reviews, finance restructuring, property management and future portfolio decisions.
Six steps to financial independence
Step
01
The discovery meeting
We begin by understanding your goals, financial position, lifestyle ambitions and long term vision. This gives the strategy a clear starting point before any property is considered.
Step
02
The finance meeting
Our in house finance team assesses borrowing capacity, lending structure and available options. This step is critical because the finance position shapes the strategy and helps determine what is realistic.
Step
03
A tailored investment proposal
Using your goals and financial position, we prepare a personalised strategy and selected property opportunities. You then work with Reventon’s Buyer’s Advocates as the plan moves from strategy to acquisition.
Step
04
Property acquisition
We negotiate on your behalf and support the purchase process. The client services team guides each stage so the property decision stays connected to the original strategy.
Step
05
Handover to property management
Once the property settles, our in house property management team helps secure tenants and maintain the property. This keeps the asset connected to the wider investment plan.
Step
06
Ongoing support
For Reventon, settlement is the beginning, not the end. We support clients through portfolio reviews, finance restructuring opportunities and long term strategic guidance.
Delivering Measurable Outcomes
We work closely with our clients to deliver structured strategies that translate into real financial progress.
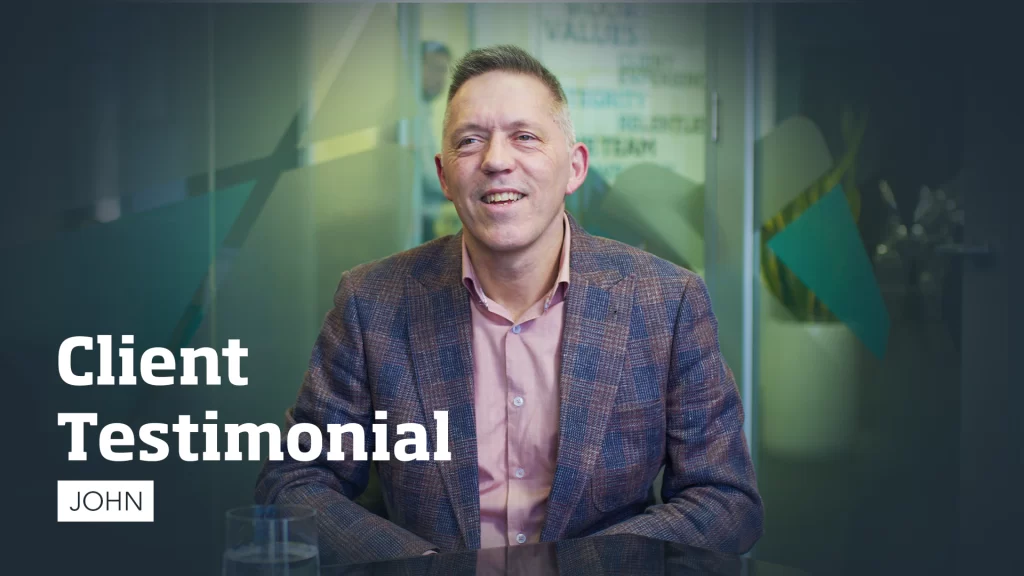
John's an engineer running a busy practice. When he first considered investing in property, he wasn’t sure where to begin. He’d spoken to a number of advisory agencies, but nothing quite felt right.
Then came a conversation with our Investment Strategist Marcus and everything changed.
Since that first call, John has built a growing portfolio of three investment properties with Reventon:
• One purchased through his super in Brisbane
• One in Adelaide
• One currently under construction in Perth
What started as uncertainty has turned into confidence, clarity, and peace of mind — knowing he’s building a strong financial future for his daughter and his family.
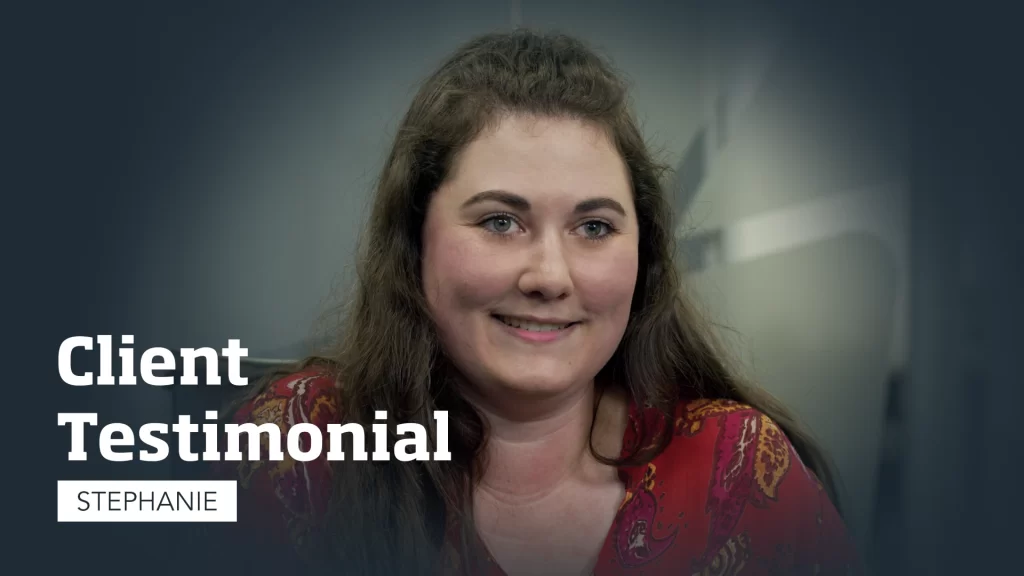
A young teacher on a single income, Stephanie knew she needed to own property if she didn't want to be renting forever, but was struggling to afford anything in Melbourne's eastern suburbs near her school. After going to a series of auctions for old apartments that were continuously going for higher prices than her borrowing capacity, she turned to Reventon to help her out.
Zen and the team at Reventon were able to find her a three bedroom new build in Perth that she could actually afford. Stephanie was actually the very first client we got into WA, and since signing over a year ago, has seen a property uplift of more than $120,000 in value.
Since filming this video, Stephanie has completed her build and secured a tenant, with weekly rent far exceeding what she was initially quoted before the build. With the Perth market continuing to tighten, we expect her property value to keep growing.
Stephanie is now Rentvesting in a spacious house with a large garden only 8 minutes drive from work. Thanks to Reventon, she's able to live the life she wants, and also have her money working hard for her.
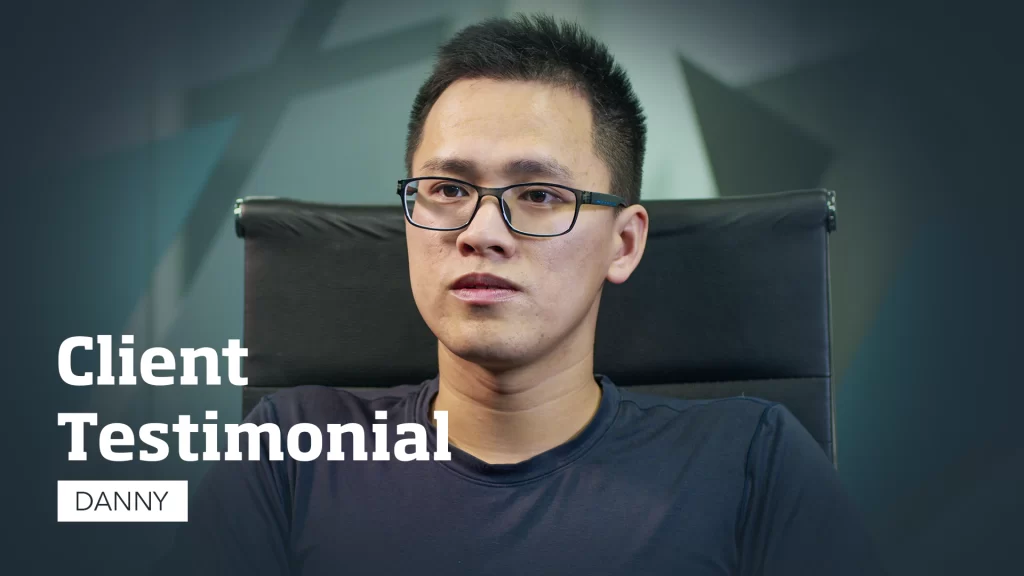
After buying his first home in Adelaide for his young family, Danny started planning out his next steps. A life-long friend of one of the Reventon staff, Danny was put in touch with George, our Senior Property Consultant.
Working with Danny, George was able to identify a prime location for Danny to invest in, and even before the build has completed, Danny has already seen massive uplift in his property value.
Working with our finance team, Danny was able to get the right loan at the right rate, to supercharge his investment journey and get him into the best position possible.
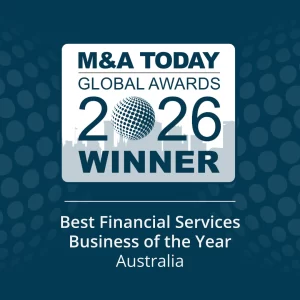
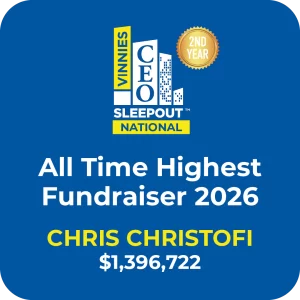
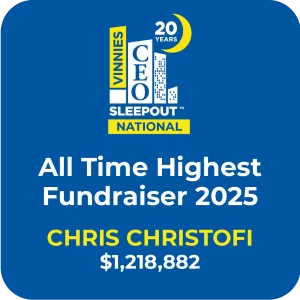
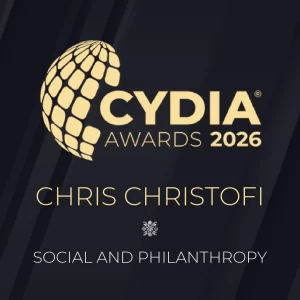
Recognised for Excellence
Reventon has been recognised across the industry for its performance, service standards, and commitment to delivering outcomes for clients. Our track record reflects a consistent focus on quality, integrity, and results.
Frequently Asked Questions
What is a property investment strategy?
A property investment strategy is a written plan that sets your goals, borrowing capacity, property criteria, purchase sequence and review points before you buy. It helps make sure each property decision supports your wider financial plan.
Do I need a strategy before I buy my first investment property?
Yes. A strategy is especially important before your first purchase because that decision can affect borrowing capacity, cash flow and your ability to buy again. A clear plan helps you understand what property type, location and price point may suit your goals.
Should I focus on capital growth or rental yield?
It depends on your income, cash flow, risk profile and portfolio stage. Some investors need stronger rental income to support serviceability. Others may be able to hold a growth focused asset for longer. Most portfolios need a balance over time.
How many investment properties do I need to retire?
There is no single number. The answer depends on your income goal, debt level, retirement timeline, property values, cash flow and other assets. A strategy should work backwards from your personal goal rather than chasing a fixed property count.
How often should my strategy be reviewed?
Your strategy should be reviewed when your income changes, interest rates move, tax rules change, equity grows, a loan needs restructuring or you are considering another purchase. Many investors benefit from a yearly review.
Can you help if I already own one property?
Yes. Reventon can review your existing property, equity position, loan structure, cash flow and rental performance before helping you decide whether to hold, refinance, buy again or adjust the strategy.
Ready to start your investment journey?
Start with a 15 minute conversation. Speak with Reventon about your goals, your finance position and what a written property investment strategy could look like.
